Flexible Coverage When You Need It
Short-Term Health Insurance
Between jobs, waiting on employer coverage, retiring before 65 or missed open enrollment? Short-term health insurance can cover you for as little as one month or as long as nearly three years. Rising Tides Benefits Group is a family-owned broker in St. Augustine that helps Florida individuals and families compare short-term plans and decide honestly whether one fits, at no cost to you.
Coverage From 1 Month to Nearly 3 Years
Apply any time of year. No open enrollment period required.
Choose your length. Plans run from one month up to nearly three years, depending on the plan.
Start fast. Once you're approved, coverage can begin as soon as the next day.
Pick your budget. Choose from a range of deductibles and coinsurance levels.
Free, Local Help Finding the Right Short-Term Plan
Short-term plans vary more than ACA plans do. Deductibles, benefit limits, prescription coverage and pre-existing condition rules all differ from plan to plan. We walk you through the fine print and make sure you know what's covered before you buy.
What you can expect:
A side-by-side comparison of plan options, lengths and deductibles
A clear explanation of what each plan does and doesn't cover
An honest recommendation on whether short-term or an ACA plan fits you better
Help with the application and health questions
Support when your plan ends, including moving to an ACA plan at open enrollment
Short-Term Plan Options
Short-Term Medical
Temporary coverage from one month up to just under a year. These plans typically cover doctor visits, urgent care, emergency room visits, hospital stays and labs, and many include prescription coverage. A good fit for a gap between jobs or while you wait for new coverage to start.
Multi-Term Plans (Nearly 3 Years)
Three back-to-back terms that add up to one day less than three years, with a single application. These plans generally offer richer benefits than traditional short-term plans, including doctor visits, urgent care and prescriptions, and some include a limited preventive care benefit after a waiting period. Because you apply once, you don't have to re-qualify each term, and some pre-existing conditions may be covered after your first 12 months.
Lower-Cost Hospital and Surgical Options
For people who mainly want protection against a large hospital bill, some plans focus on hospital and surgical care at a lower premium.
Dental, Vision and Accident Add-Ons
Round out a short-term plan with stand-alone dental, vision or accident coverage.
Short-Term Health vs. ACA Marketplace Plans
Who short-term health is a good fit for
People between jobs or waiting for employer coverage to start
Early retirees bridging the gap to Medicare at 65
Healthy people who don't qualify for an ACA tax credit and want a lower premium
Anyone who missed ACA open enrollment and doesn't qualify for a Special Enrollment Period
When an ACA plan is the better choice
You have a pre-existing condition, or are pregnant or planning a pregnancy
You qualify for a premium tax credit; short-term plans aren't eligible for financial help
You need guaranteed coverage. Short-term plans use medical underwriting and can decline an application
Not sure which you need? See our ACA Marketplace page or book a free consultation.
Getting Covered Is Simple
1. A quick call or online quote
Tell us who needs coverage, how long you need it, your doctors and any prescriptions.
2. Compare your options honestly
We show you short-term options side by side, and an ACA plan too if it's a better fit, with premiums, deductibles and limits in plain English.
3. Apply, then we stay with you
We help you complete the application and health questions. When your plan is ending, we help you plan what comes next.
Why Florida Families Choose Rising Tides
Local and family-owned
We're based in
St. Augustine and know Florida's insurance market.
Honest advice
We'll tell you when
short-term health isn't
the right fit, even if it
means recommending
a different plan.
Award-winning
Business Rate named us Best Health Insurance Agency in
St. Augustine for 2024.
One broker for every stage
Short-term, ACA, Medicare and supplemental coverage, all with one local team.
"He has helped us with many things including a 'bridge policy' to cover me for time in-between employee coverage and Medicare." — Melissa S.
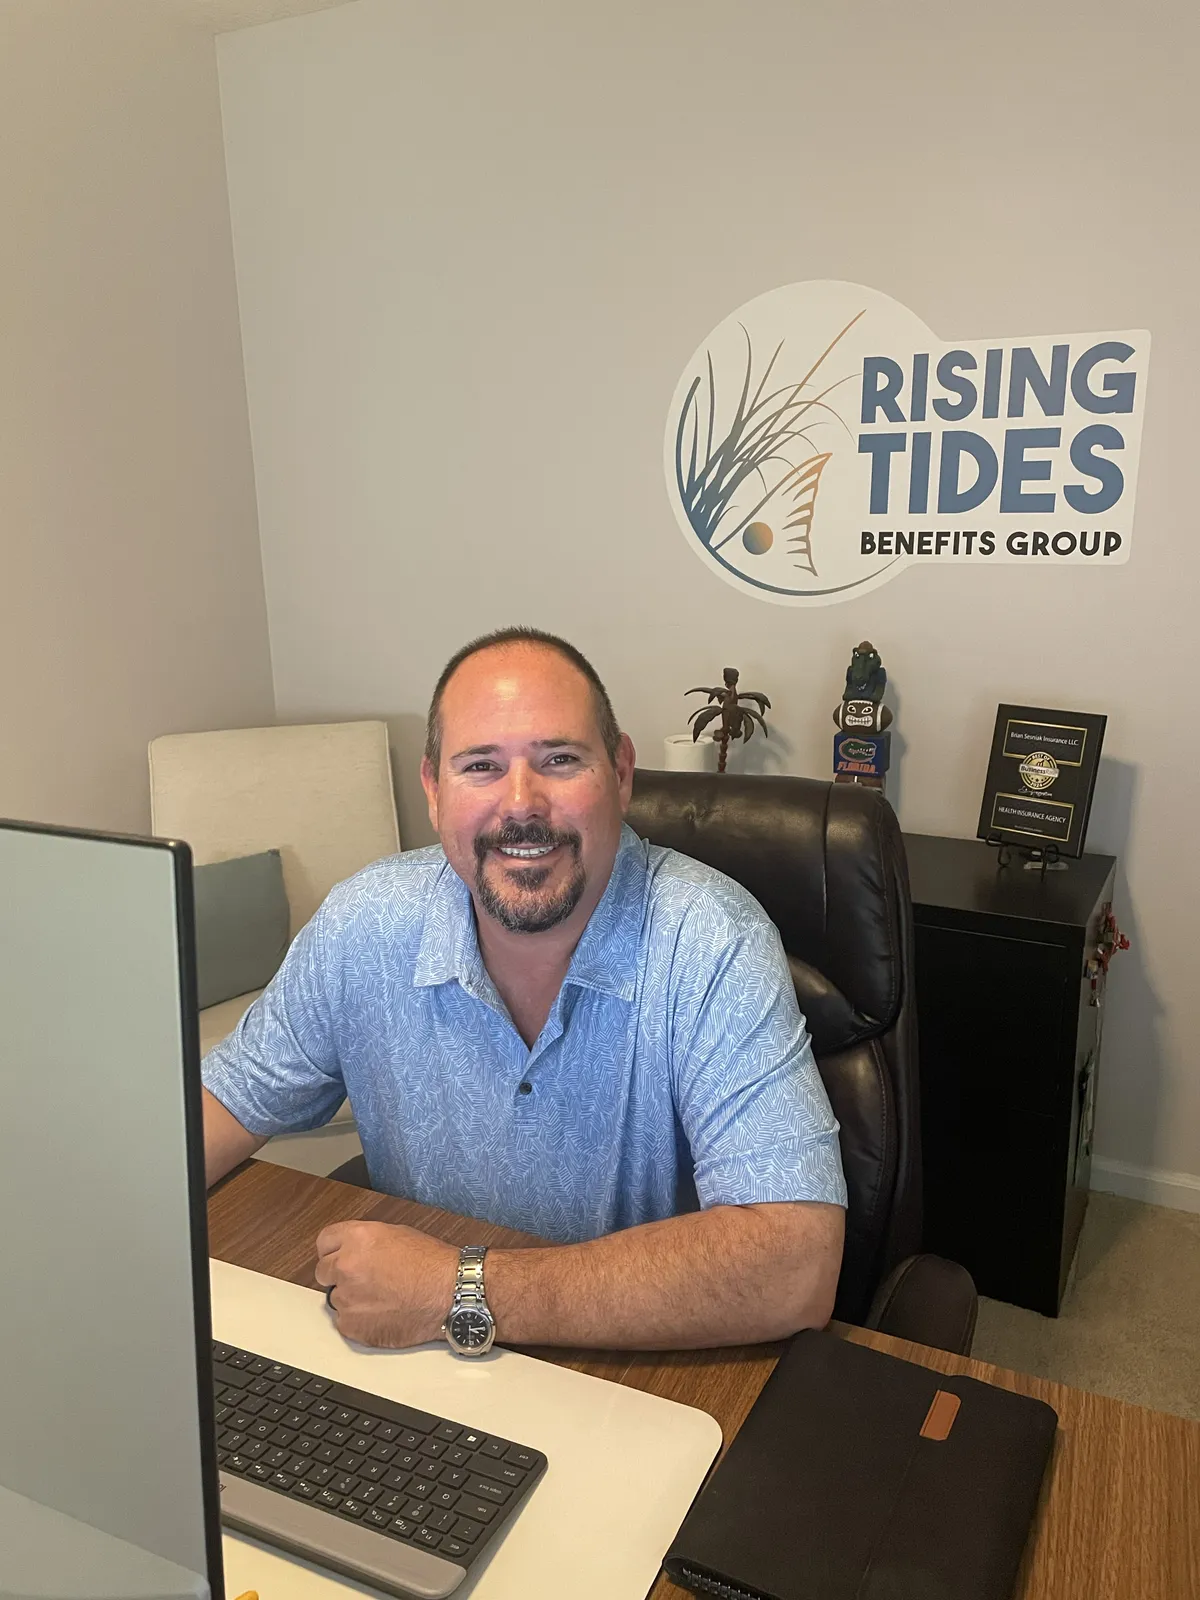
Meet the Founder & CEO
Hey, I'm Brian Sesniak
I've helped Florida families and businesses with their insurance since 2019. After my son's 81-day NICU stay brought more than $4 million in medical bills, my mission became simple: no family or business should face a health crisis without the right coverage and someone in their corner. That's why I'm here for every client I serve.
Short-Term Health Insurance FAQs
Is short-term health insurance the same as an ACA plan?
No. Short-term plans aren't required to follow the Affordable Care Act's rules. They can exclude pre-existing conditions, limit benefits like maternity and mental health care, and set annual or lifetime dollar limits. They also aren't eligible for ACA tax credits.
How long can I keep a short-term plan in Florida?
Florida allows short-term plans with an initial term of less than 12 months and a total of up to 36 months including renewals. Depending on the plan, you can choose from one month up to one day less than three years.
Does short-term health insurance cover pre-existing conditions?
Generally not. Short-term plans use medical underwriting, ask health questions and can decline an application. Some multi-term plans may cover certain pre-existing conditions after the first 12 months. If you have ongoing health needs, an ACA plan is usually the safer choice.
Can I buy short-term health insurance any time?
Yes. Unlike ACA plans, short-term plans aren't limited to open enrollment. Once you're approved, coverage can start as soon as the next day.
What happens when my short-term plan ends?
You may have to wait for ACA open enrollment (November 1 to January 15) to get an ACA plan, because a short-term plan ending usually doesn't qualify you for a Special Enrollment Period. We'll help you time your coverage so you're not left with a gap.
Who can apply?
Short-term plans are available to individuals and families in Florida who meet the plan's health and age requirements. Age limits vary by plan; for example, some multi-term plans accept applicants ages 19 through 63.
Ready to Get Covered?
Get an instant quote online, or book a free consultation with our St. Augustine team. We'll help you find the right coverage for as long as you need it.
This coverage is not required to comply with certain federal market requirements for health insurance, principally those contained in the Patient Protection and Affordable Care Act. Be sure to check your policy carefully to make sure you are aware of any exclusions or limitations regarding coverage of preexisting conditions or health benefits (such as hospitalization, emergency services, maternity care, preventive care, prescription drugs, and mental health and substance use disorder services). Your policy might also have lifetime and/or annual dollar limits on health benefits. If this coverage expires or you lose eligibility for this coverage, you might have to wait until an open enrollment period to get other health insurance coverage.


© 2026 Rising Tides Benefits Group. All rights reserved.
Not a government website. Rising Tides Benefits Group is not affiliated with, endorsed by, or connected to the Centers for Medicare & Medicaid Services (CMS), the U.S. Department of Health and Human Services, or any federal or state government agency. We do not offer every product available in your area. Please contact Medicare.gov, 1-800-MEDICARE, or your local State Health Insurance Program (SHIP) to get information on all of your options. We are licensed, independent insurance broker. We represent multiple insurance carriers and may receive compensation from the carriers whose plans we sell. This does not affect the cost of your plan.