Medicare Made Simple
Medicare Advantage, Medigap & Part D Plans
Turning 65, retiring or reviewing your plan for 2027? Rising Tides Benefits Group is a family-owned, independent Medicare broker in St. Augustine. We compare Medicare Advantage, Medicare Supplement (Medigap) and Part D drug plans from multiple insurance companies, check that your doctors and prescriptions are covered and help you enroll, at no cost to you.
Medicare Open Enrollment:
Oct 15 - Dec 7, 2026
During Open Enrollment, you can switch Medicare Advantage plans, change Part D drug plans, or move between Original Medicare and Medicare Advantage. Your new plan must receive your request by December 7, and coverage starts January 1, 2027.
Plans change every year. Check the Annual Notice of Change your plan mailed you for 2027 changes to premiums, copays, drug coverage and networks, then let us compare it against other plans in your area.
Free, Local Help Choosing Your Medicare Coverage
Medicare has a lot of moving parts: Parts A, B, C and D, Medigap letters, networks, drug lists and enrollment deadlines with penalties for missing them. We walk you through it in plain English and stay with you after you enroll.
What you can expect:
A side-by-side comparison of plans from multiple insurance companies
A check that your doctors, hospitals and pharmacies are in network
A drug cost review using your actual prescriptions
Help avoiding late enrollment penalties when you first sign up
An annual review every fall, plus year-round help with claims and billing questions
Medicare Coverage Options We Help With
Medicare Advantage (Part C)
All-in-one plans from private insurers that cover everything Original Medicare does, usually with drug coverage and extras like dental, vision or hearing. Costs, networks and benefits vary by plan, and every plan has a yearly out-of-pocket limit. You must keep paying your Part B premium.
Medicare Supplement (Medigap)
Works alongside Original Medicare to help pay deductibles, copays and coinsurance, and lets you see any doctor nationwide who accepts Medicare. Plans are standardized by letter, so a Plan G offers the same benefits from every insurer; only the price differs. Plans C and F aren't available to people who became eligible for Medicare on or after January 1, 2020.
Part D Prescription Drug Plans
Stand-alone drug coverage to pair with Original Medicare and a Medigap plan. We compare plans using your exact prescriptions and preferred pharmacy, because the plan with the lowest premium isn't always the lowest total cost.
Turning 65 and Retiring
We help you decide when to enroll in Parts A and B, whether to keep or drop employer coverage, and how to avoid late enrollment penalties. Many of our Medicare clients first came to us for individual or group coverage, so we can bridge you straight from your current plan to Medicare.
What's Changing for 2027
Higher Part D drug cost cap
The yearly cap on what you pay out of pocket for covered Part D drugs rises to $2,400 in 2027, up from $2,100 in 2026. Once you reach it, you pay nothing more for covered drugs for the rest of the year.
Higher Part D deductible
The maximum Part D deductible a plan can charge rises to $700 in 2027, up from $615. Many plans charge less, which is one reason comparing plans matters.
Stand-alone drug plan premiums may rise
A temporary federal program that held down stand-alone Part D premiums ended after 2026, so 2027 premiums are set without it. If your drug plan's premium jumped, it's worth comparing.
Part B premium and deductible
CMS announces the 2027 Part B premium and deductible in the fall. For 2026, the standard Part B premium is $202.90 a month and the deductible is $283.
Insulin stays capped
Covered insulin under Part D still costs no more than $35 for a month's supply.
Key Medicare Enrollment Periods
Initial Enrollment Period
Seven months around your 65th birthday: the three months before your birthday month, the month itself and the three months after. Enrolling on time helps you avoid lifelong late enrollment penalties.
Medigap Open Enrollment
A one-time, six-month window that starts the first month you have Part B and are 65 or older. During it, insurers can't deny you a Medigap policy because of health problems. After it ends, you may not be able to buy one, or it may cost more.
Medicare Open Enrollment
October 15 to December 7 every year. Switch Medicare Advantage or Part D plans, or move between Original Medicare and Medicare Advantage, with changes starting January 1.
Medicare Advantage Open Enrollment
January 1 to March 31, for people already in a Medicare Advantage plan. You can switch to another Medicare Advantage plan or return to Original Medicare and join a drug plan.
Special Enrollment Periods
Certain life events, such as moving, losing other coverage, or qualifying for Medicaid or Extra Help, let you change plans outside the usual windows.
Get Started Is Simple
1. A quick conversation
Tell us about your doctors, prescriptions, budget and how you like to get care.
2. Compare your options side by side
We show you Medicare Advantage, Medigap and Part D options available in your area, with premiums, out-of-pocket costs and network details in plain English.
3. We enroll you, then stay with you
We help you enroll and stay your point of contact for claims and billing questions, and we review your coverage with you every fall.
Why Floridians Choose Rising Tides for Medicare
Local and family-owned
Based in St. Augustine and know the plans and provider networks in Northeast Florida.
Independent
We work with multiple insurance companies, so we can compare all your options.
With you every year
Plans change every year. We review yours each fall so you're never surprised in January.
Award-winning
Business Rate named us Best Health Insurance Agency in St. Augustine for 2024.
"Brian helped us with insurance prior to qualifying for Medicare and then navigating Medicare Part D and Medicare Supplement insurance. He continues to provide valuable guidance since retirement." — Ken S.
"He has helped us with many things including a 'bridge policy' to cover me for time in-between employee coverage and Medicare. He also helped us pick the best supplemental policy and RX policy when it came time for Medicare." — Melissa S.
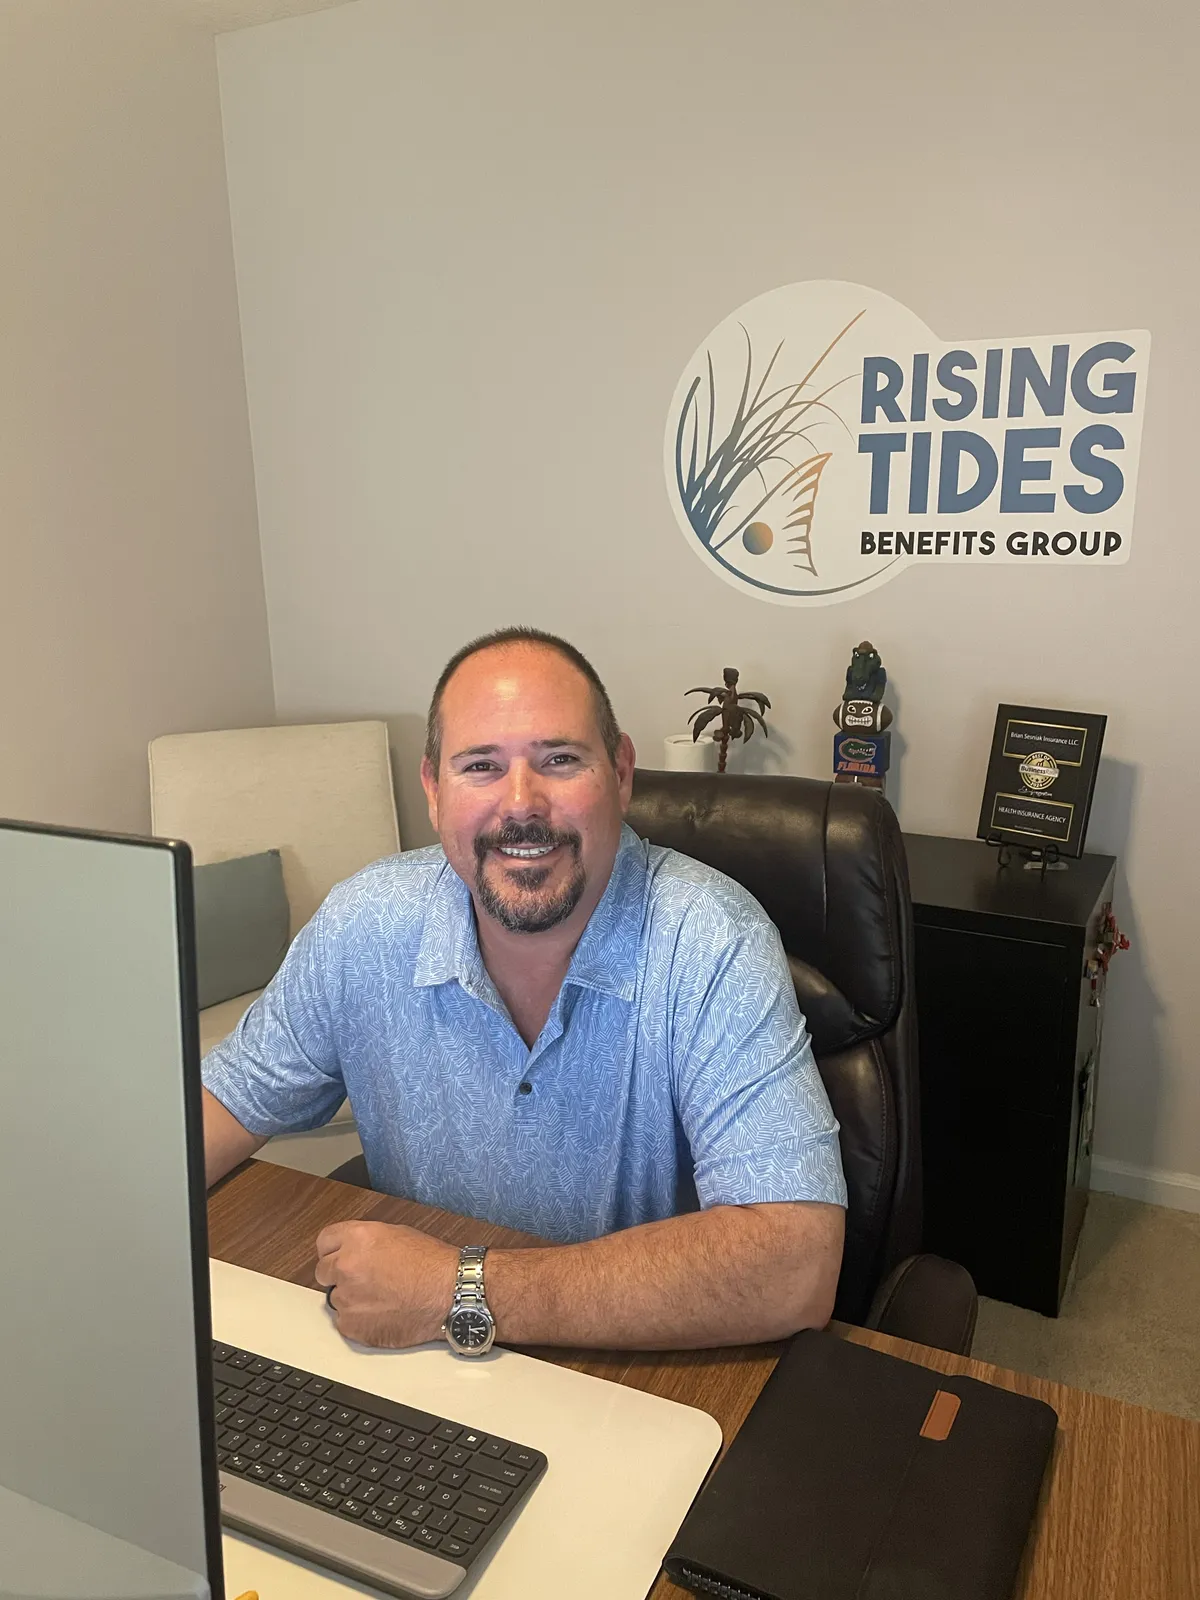
Meet Brian Sesniak
I've helped Florida families and businesses with their insurance since 2019. After my son's 81-day NICU stay brought more than $4 million in medical bills, my mission became simple: no family or business should face a health crisis without the right coverage and someone in their corner. That's why I'm here for every client I serve.
Medicare FAQs
Does it cost more to use a Medicare broker?
No. Plan prices are set by the insurance companies and are the same whether you enroll on your own or with us. Insurers pay brokers, so our help is free to you.
When should I sign up for Medicare?
Most people should enroll during their seven-month Initial Enrollment Period around their 65th birthday. If you're still working and have employer coverage, you may be able to delay Part B without a penalty. We'll help you check before you decide.
What's the difference between Medicare Advantage and Medigap?
Medicare Advantage replaces how you get Original Medicare benefits, usually with a network, copays and a yearly out-of-pocket limit. Medigap supplements Original Medicare, paying some or all of your out-of-pocket costs and letting you see any doctor who accepts Medicare. You can't have both at the same time.
What is the most I'll pay for prescriptions in 2027?
The 2027 out-of-pocket cap for covered Part D drugs is $2,400. After you reach it, you pay nothing more for covered drugs that year.
Can I change my Medicare plan if I'm unhappy with it?
Yes, during Open Enrollment (October 15 to December 7) for changes starting January 1. If you're in a Medicare Advantage plan, you also get a second chance from January 1 to March 31.
Will my plan cover me if I travel or spend part of the year in another state?
It depends. Many Medicare Advantage plans have local networks, while Medigap works with any provider nationwide who accepts Medicare. Tell us where you spend your time and we'll find coverage that fits.
Ready to Review Your Medicare Options?
Book a free Medicare review with our St. Augustine team before Open Enrollment ends December 7. We'll compare your current plan with your 2027 options and help you decide with confidence.


© 2026 Rising Tides Benefits Group. All rights reserved.
Not a government website. Rising Tides Benefits Group is not affiliated with, endorsed by, or connected to the Centers for Medicare & Medicaid Services (CMS), the U.S. Department of Health and Human Services, or any federal or state government agency. We do not offer every product available in your area. Please contact Medicare.gov, 1-800-MEDICARE, or your local State Health Insurance Program (SHIP) to get information on all of your options. We are licensed, independent insurance broker. We represent multiple insurance carriers and may receive compensation from the carriers whose plans we sell. This does not affect the cost of your plan.